
Kling AI Raised $2.9B at a $17.9B Valuation. Now Comes the Audit
Kling AI has closed the largest financing round any AI video company has seen. Reports put the money received at roughly $2.9 billion, with a post-money valuation of about $17.9 billion — Alibaba, Tencent and Baidu all participating, and a planned spin-off from Kuaishou that points toward a Hong Kong listing next year.
That is a lot of capital for a product category that did not exist three years ago. It also means Kling AI is about to face the thing every private AI company avoids: an actual audit.
This is what the numbers say, what they leave out, and what changes when a video model has to report to shareholders instead of venture investors.
What Actually Happened
The mechanics, as reported:
The round. Kling AI received roughly $2.9 billion at a post-money valuation near $17.9 billion. Reports differ on the exact figure — some say $2 billion, some $2.8 billion, some $2.9 billion, with valuations reported between $15 billion and $18 billion. The differences appear to reflect different stages of the round and different reporting dates rather than disagreement about the underlying deal.
The investors. Alibaba, Tencent and Baidu — three companies that compete with each other and with Kuaishou in generative AI, all funding the same asset.
The structure. Kling AI is being spun out of Kuaishou, its parent, rather than staying an internal business unit.
The exit path. A Hong Kong IPO for Kling AI is reportedly targeted for next year, with Bloomberg reporting an ambition to raise around $1 billion.
The Numbers Behind the Valuation
Two figures make the $17.9 billion legible.
Users. Kling AI reported more than 100 million global users.
Revenue. Kling AI reported quarterly revenue above ¥650 million — call it roughly $90 million, which annualises to something in the region of $360 million.
Run the arithmetic on Kling AI and the valuation lands near 50 times annualised revenue. That is a growth multiple, not a value multiple: it prices Kling AI as a company that will keep compounding, not one that will settle into a profitable plateau.
Which is exactly why an IPO matters for Kling AI. Private investors can pay for a story. Public markets ask for a margin.
Why Alibaba, Tencent and Baidu All Bought In
The investor list is the most interesting part of the round, and it is not an endorsement of Kling AI in the way it first appears.
All three are building their own video generation. All three have their own cloud businesses that would like to host other people's models. Buying into Kling AI is not a bet that it will beat them — it is a hedge that ensures none of them is locked out if it does.
That is normal behaviour in a capital-intensive category with an unclear winner. It also means the round should not be read as a verdict on Kling AI's technology. Strategic money in Kling AI buys optionality, not conviction.
The Quality Question Is Settled. The Money Question Is Not.
Worth connecting this to what was measured two weeks ago. An evaluation out of the University of Hong Kong found Chinese video models leading on visual quality — Kling AI's category peers in front of Veo 3.1 and Sora 2 Pro — while trailing on safeguards.
Read the two stories together and the pattern for Kling AI is clear. Capital is pricing the quality result and discounting the safety result. Investors are buying output fidelity, because output fidelity is what customers pay for. Whether the safety gap eventually becomes a cost — through regulation, platform policy, or enterprise procurement — is the open question the valuation implicitly answers with "not yet".
What a Spinoff and an IPO Actually Change
Three things shift for Kling AI the moment it becomes a separate listed entity.
Unit economics become public. Today the numbers are quarterly revenue and user counts for Kling AI. After a listing, the questions are gross margin, compute cost per generated second, and customer acquisition cost. Those are harder numbers to make look good, because inference is expensive and Kling AI runs a lot of it.
Growth has to survive comparison. A spin-off is judged against its former parent and against listed peers simultaneously. That is where the Chinese business press framing becomes relevant — the recurring question of whether Kling AI can become a genuine second growth curve rather than a well-funded side project.
Competitive pressure gets financial. ByteDance's Seedance line, Runway, Google's Veo and OpenAI's Sora are all competing for the same customers. When Kling AI is private, a price war is a strategic choice. When it is public, a price war is a margin problem reported every quarter.
Read the Valuation With Care
Four honest caveats.
Reported figures for Kling AI genuinely vary. Anywhere from $2 billion to $3 billion raised, and $15 billion to $18 billion valuation, depending on the outlet. Anyone quoting one number as definitive is simplifying.
Revenue is not profit. No profit figures for Kling AI have been published. A company growing at this pace is plausibly reinvesting everything it earns into compute.
User counts need definition. "100 million global users" almost certainly counts registered accounts, not active paying customers. The number that matters for the valuation is the one Kling AI has not published: paid conversion.
A targeted IPO is not a filed IPO. Reports describe an ambition for next year. Filing, pricing and listing are three separate events, and the timeline can move.
What This Means If You Use AI Video
Two practical consequences, pointing in opposite directions.
Prices probably fall first. Kling AI raising this much money buys compute at scale, and scale is how inference gets cheaper. Expect aggressive pricing while everyone fights for share.
Then they may rise. A public Kling AI needs margin. The comfortable assumption that AI video gets cheaper forever is a private-market assumption about Kling AI and its peers — it survives right up until the first earnings call.
The practical response to both: do not build a workflow that depends on one vendor's price. Whatever Kling AI and its competitors charge next year, the model you can swap out cheaply is the model that cannot hurt you.
A Prompt to Try
If you are evaluating Kling AI against anything else, test the thing that separates video models: sustained motion in a single unbroken shot.
Copy & Paste this into Fanch AI (Model: gpt_image_2):
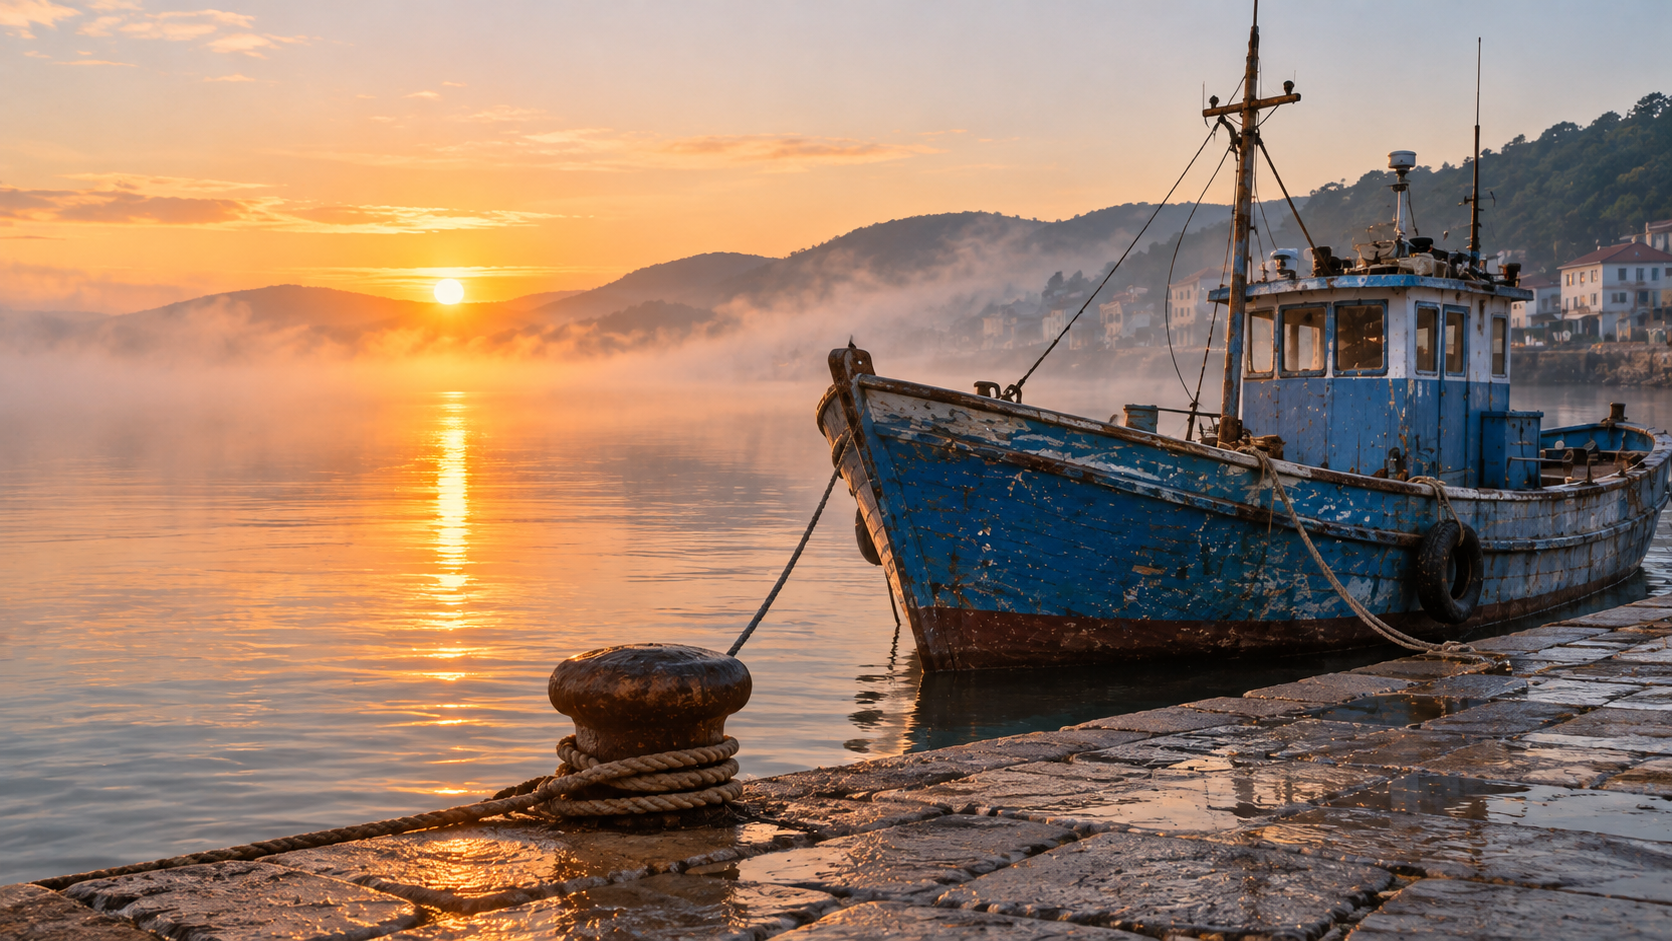
A cinematic still of a harbour at dawn seen from a low stone quay: mist sitting on the water, a single wooden fishing boat with a worn blue hull, distant hills fading into pale haze, warm sun breaking low on the horizon and catching the ripples. Fine detail in the wet stone and the boat's weathered paint, muted blue and amber palette, shallow depth of field, 16:9 framing, 8K detail, no people, no text overlay.
Lock that frame, animate it, and watch whether the mist and the ripple stay consistent across ten seconds. That is where Kling AI and its rivals actually differ.
Why Fanch AI Fits
A $17.9 billion valuation is a bet that video generation becomes infrastructure. That makes the model choice a procurement decision, not a loyalty one — and for Kling AI specifically, a valuation is not a quality guarantee. — and the cheap way to decide is to compare models on a frame you already control.
Fanch AI gives you a dedicated image model you direct with precise prompts, so you can settle composition and light before spending on video generation with Kling AI or anything else.